Incorporation Relief: Moving a Sole Trade Into a Company Without Triggering CGT
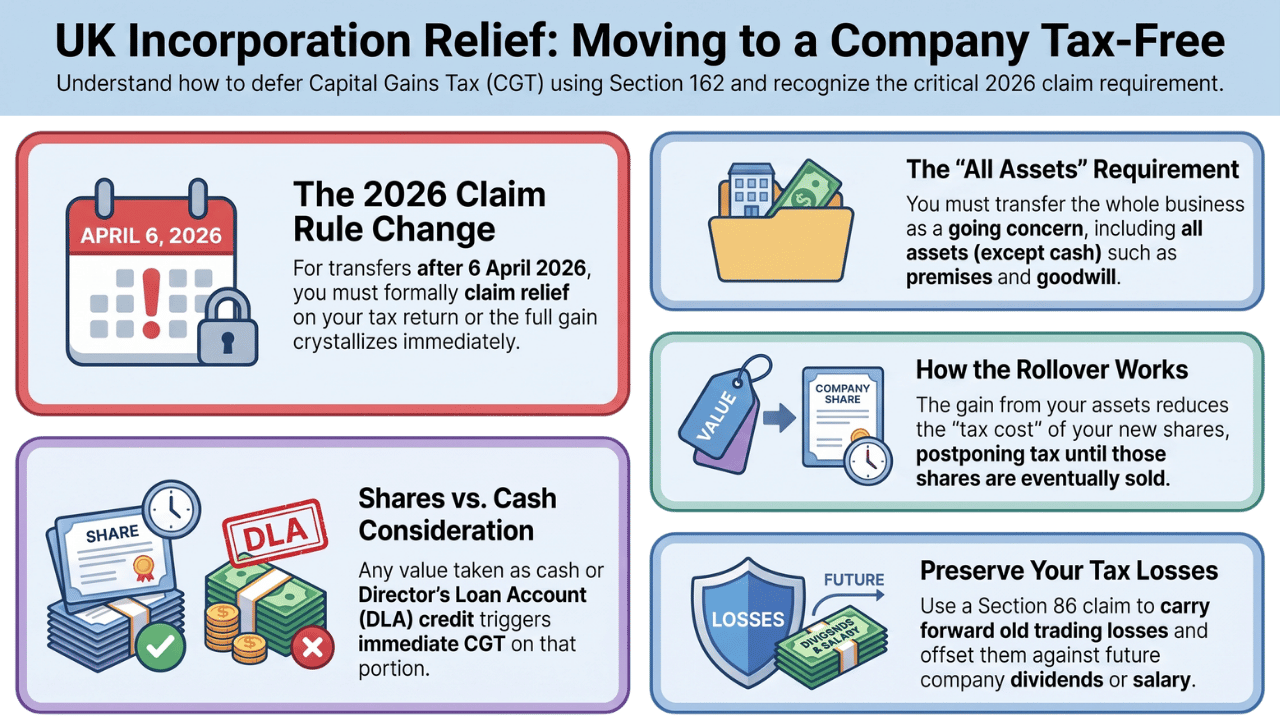
Incorporation relief under section 162 of the Taxation of Chargeable Gains Act 1992 allows a sole trader or partnership to transfer their business into a limited company without an immediate Capital Gains Tax (CGT) charge, by rolling the gain into the base cost of the shares received. For transfers taking place on or after 6 April 2026, HMRC’s own policy paper on the claims process confirms this relief is no longer automatic. It must now be actively claimed on the transferor’s Self Assessment return for the tax year of the transfer, a change introduced by Finance Act 2026 that fundamentally alters how careful the paperwork around an incorporation needs to be.
This is genuinely the most important development in this area for years, and it catches out anyone relying on older material that still describes the relief as something that simply applies in the background provided the conditions are met. For any incorporation completing in the current tax year, treating the claim as a formality is no longer an option.
The Conditions That Must Be Met
Incorporation relief applies where an individual, or a partner in a partnership, transfers a business as a going concern, together with the whole of its assets, or the whole of its assets other than cash, to a company, wholly or partly in exchange for shares. Every element of that sentence carries weight. The business must be transferred as a going concern, not as a collection of individual assets sold off separately. Every asset, other than cash, generally needs to go into the company; deliberately retaining one valuable asset, keeping a single investment property back while transferring the rest of a portfolio, for example, will usually disqualify relief on the assets that are transferred, not just the one held back. HMRC’s practice, under an established concession, does not treat outstanding business liabilities taken over by the company as non-share consideration, so novating debt alongside the assets does not, on its own, threaten the relief.
The consideration for the transfer must be wholly or partly in shares. Where part of the consideration is cash, or credited to a director’s loan account rather than issued as shares, the amount of gain that can be rolled over is reduced proportionately, with the cash element remaining chargeable to CGT in the ordinary way.
Incorporation Relief (s162 TCGA 1992)
Transfer a sole trade or partnership into a UK Limited Company without paying an upfront Capital Gains Tax (CGT) charge. Learn how gains roll over, what qualifies, and critical new compliance rules.
How Section 162 Roll-Over Relief Works
When you exchange business assets for shares, the capital gain is deferred by reducing the base cost of your new shares. Any cash or Director’s Loan Account (DLA) credit received triggers an immediate CGT charge proportionally.
Input Business Transfer Values
Tax Impact on Incorporation
Notice how the rolled-over gain is deferred, not eliminated: the shares carry a reduced base cost of £0.
All 5 Statutory Conditions Must Be Met
Failing even one condition disqualifies the entire relief across all assets. Use this interactive check to evaluate your proposed incorporation.
Please check the conditions above that apply to your transaction.
Incorporating a Buy-to-Let / Property Portfolio?
Property letting is ordinarily deemed a passive investment by HMRC, which disqualifies it from Incorporation Relief. However, under the Ramsay benchmark, a property business can qualify if there is a sufficient degree of active personal management.
Should You Claim Relief or Pay Tax Now?
Since relief is no longer automatic from 6 April 2026, transferors can deliberately choose not to claim relief in order to crystallise their gain at Business Asset Disposal Relief (BADR) rates or absorb available capital losses.
Claim Full Incorporation Relief
- ✔ £0 Upfront CGT: Total gain is deferred into the base cost of your company shares.
- ✔ Cash Conservation: Protects working capital when business liquidity is required elsewhere.
- ✖ Zero Base Cost: Future sale of company shares triggers deferred gain at prevailing CGT rates.
- ✖ Unused Allowances: Annual exempt amounts or existing capital losses may be wasted.
Crystallise at BADR / Standard Rates
- ✔ Full Base Cost Established: Shares acquired at true Market Value, minimising future exit taxes.
- ✔ Lock In BADR Rate: Utilise the BADR lifetime limit (18% in 2026/27) rather than higher future rates.
- ✔ Director’s Loan Creation: Creates a substantial tax-free DLA that can be drawn down tax-free.
- ✖ Immediate Cash Tax: CGT is payable on 31 January following the end of the tax year.
Incorporation Relief ONLY Defers CGT — Not Property Stamp Taxes!
Because the transfer to your own company is a transaction between connected persons, Stamp Duty Land Tax is levied at the property’s Market Value under Section 53 Finance Act 2003, regardless of whether shares or cash are exchanged.
SDLT
Administered by HMRC. Charged at market value. Note higher surcharge rates on corporate residential acquisitions.
LBTT
Land and Buildings Transaction Tax administered by Revenue Scotland. Distinct tax bands and ADS rules apply.
LTT
Land Transaction Tax administered by Welsh Revenue Authority (WRA). Calculated on market value of Welsh property.
Finance Act 2026 Changes at a Glance
Relief was automatic. Taxpayers did not report gains if criteria were met. Disapplication required an active section 162A election out.
Relief must be claimed on your Self Assessment return with full computations. Section 162A is repealed. Forgetting to claim triggers full CGT!
The Biggest Change for 2026/27: Relief Is No Longer Automatic
Until 5 April 2026, incorporation relief applied without any formal claim, provided the underlying conditions were satisfied. A taxpayer simply did not report a gain on the incorporation, relying on the conditions being met rather than notifying HMRC of anything specific. Finance Act 2026 changes this fundamentally. HMRC’s guidance confirms that for transfers of a business on or after 6 April 2026, a claim for incorporation relief will be required by the transferor, made on their Self Assessment return for the tax year in which the transfer takes place, including brief details of the transaction, the tax computations involved, and the type of business transferred. This applies to individuals, partners in a partnership, and trustees alike.
Alongside this, section 162A, the provision that previously allowed a transferor to formally elect out of relief if they did not want it, has been repealed. This makes procedural sense once relief becomes claim-based rather than automatic: there is no longer any need to elect out of something that only applies if you actively ask for it in the first place. If you would prefer to crystallise a gain now, perhaps to use Business Asset Disposal Relief (BADR) or your annual exempt amount, you simply do not make the claim, rather than submitting a separate disapplication election.
What Happens If You Forget to Claim
This is where the practical risk sits for anyone incorporating from April 2026 onward. Under the previous automatic system, an adviser who failed to spot that incorporation relief applied caused no immediate harm, since the relief operated regardless of whether anyone actively thought about it. Under the new system, a transferor who completes an incorporation but fails to make the claim on their return for that tax year has, in principle, simply not obtained the relief, potentially leaving a substantial, unplanned CGT liability on assets, land, goodwill, that have already left their personal ownership. Given the scale of gains that can be involved in incorporating a business built up over many years, this is not a paperwork detail to leave until the Self Assessment deadline is looming. It needs to be built into the completion process itself, with the claim prepared alongside, not after, the transfer documentation.
How the Relief Actually Works
Where the conditions are met and the claim is properly made, the gain that would otherwise arise on the transfer of each qualifying business asset, calculated in the normal way, is not charged to CGT immediately. Instead, it is rolled over, reducing the base cost of the shares received in exchange. The tax is not eliminated, only deferred, until the shares themselves are eventually sold, at which point the deferred gain, along with any further growth in the shares’ value, becomes chargeable.
Take a sole trader whose business, including goodwill, equipment, and a small commercial unit, is agreed to have a chargeable gain of £340,000 on incorporation. In exchange for transferring the whole business, they receive shares in the new company worth £340,000. Provided the claim is properly made, no CGT arises on the incorporation itself. Instead, the base cost of the shares is reduced by the full £340,000 gain, meaning the shares are treated as having been acquired for nil. If those shares are later sold for £500,000, the full £500,000 becomes chargeable at that point, not just the growth since incorporation, since the earlier deferral is built into the reduced base cost carried forward.
Where part of the consideration is cash rather than shares, relief is restricted proportionally. If the same business had instead been transferred for £270,000 of shares and £70,000 credited to a director’s loan account, only the proportion of the gain relating to the share consideration, roughly 79%, would be eligible for roll-over, with the remaining gain attributable to the cash element chargeable to CGT immediately in the ordinary way, potentially at BADR rates if separately available.
Goodwill: Deferred for CGT, But No Corporation Tax Benefit
Goodwill is frequently the single largest asset in a service-based sole trade being incorporated, and it qualifies fully for incorporation relief in the same way as any other business asset. The CGT gain on goodwill can be rolled over into the base cost of the shares just as with any other asset transferred. However, a restriction introduced for transfers on or after 3 December 2014 means that where the individual transferring the goodwill holds, directly or indirectly, 5% or more of the company’s shares, the company itself cannot claim a Corporation Tax deduction for amortisation of that goodwill under the intangible assets regime. The goodwill still appears as an asset on the company’s balance sheet, but it generates no ongoing tax relief for the company going forward, even though the individual has successfully deferred their own personal CGT liability on it. This is a genuine, permanent asymmetry worth explaining clearly to any client incorporating a business with substantial personal goodwill, since it means the tax benefit of incorporation relief sits entirely with the individual, not the company.
Property Businesses: Do You Actually Have a “Business”?
Incorporation relief was designed around trading businesses, but it extends to any activity that constitutes a “business” for these purposes, and property letting sits in a genuinely contested area here. HMRC has historically resisted the idea that simply owning and letting investment property amounts to a business, and there is no statutory definition settling the point either way. HMRC’s own guidance acknowledges this is a question of fact, stating plainly that it is not easy to draw the line and each case must be judged on its own facts.
The leading case on this point is Elizabeth Moyne Ramsay v HMRC, where the tribunal found that the taxpayer’s letting activity did amount to a business, on the basis that she spent, on average, around 20 hours a week actively managing the property portfolio, well beyond passive collection of rent. The tribunal’s reasoning has become the practical benchmark advisers work from: it is the degree of activity as a whole that matters, not simply the number of properties or lettings involved. Following the case, HMRC updated its own internal guidance to reflect this test, looking at factors including the range and diversity of activities undertaken, whether the work is comparable to what a commercial property business would ordinarily carry out, and the time genuinely committed to managing the portfolio rather than delegated entirely to a letting agent.
A Worked Example
Take a landlord with eleven residential properties who personally handles tenant sourcing, maintenance coordination, rent collection, and compliance across the whole portfolio, spending upward of 20 hours most weeks on the activity, well documented through contemporaneous records. This looks considerably closer to the Ramsay benchmark than a landlord with the same eleven properties who has delegated everything to a managing agent and does little beyond reviewing monthly statements. For the second landlord, HMRC would likely take the view that the activity remains passive investment rather than a business, meaning incorporation relief would not be available on transferring the portfolio into a company at all, regardless of how the transfer is structured. Given how much turns on this factual question, keeping a genuine, contemporaneous record of time spent and activities undertaken, well before any incorporation is contemplated, is far more useful than trying to reconstruct that evidence retrospectively once HMRC raises the point.
SDLT and Stamp Duty: The Costs Incorporation Relief Doesn’t Touch
Incorporation relief only addresses CGT. Where land or property is transferred as part of the incorporation, Stamp Duty Land Tax (SDLT) is charged in the ordinary way, and because the transfer is between connected persons, the consideration for SDLT purposes is the market value of the property, not the amount actually paid or the value of shares issued, regardless of how the CGT side of the transaction is structured. This is frequently the single largest actual cash cost of incorporating a property business, since a substantial portfolio incorporated at full market value can generate an SDLT bill running into tens of thousands of pounds, entirely separate from, and unaffected by, whether incorporation relief successfully defers the CGT. Where shares in other companies form part of the assets transferred, stamp duty at 0.5% may also apply on that element, though goodwill itself, not being stock or a marketable security, attracts no stamp duty.
When You Might Not Want the Relief
Because incorporation relief now requires an active claim rather than applying by default, deciding not to claim it has become the simpler, more natural default position where deferral is not actually the right outcome. There are several genuine reasons a transferor might prefer to crystallise the gain now rather than defer it. Where unused capital losses or annual exempt amount would otherwise go to waste, triggering the gain immediately allows them to be used. Where BADR remains available on the disposal, paying CGT now at the 2026/27 BADR rate of 18% may be more attractive than deferring the gain into shares that will eventually be taxed at standard rates, particularly given BADR’s rate has already risen from the 10% that applied before April 2025 and is unlikely to fall back. And crystallising the gain now, rather than rolling it into share base cost, establishes a higher base cost for the shares themselves, useful where a sale of the company is anticipated relatively soon after incorporation.
Scotland and Wales: CGT Is Reserved, But Property Transfer Tax Is Not
Capital Gains Tax, and therefore incorporation relief itself, is reserved to the UK government and applies identically to a business incorporated in Scotland, Wales, or England. Where the position genuinely diverges is the tax charged on any land or property transferred as part of the incorporation. Scotland does not use SDLT at all; property transfers there are instead charged under Land and Buildings Transaction Tax (LBTT), administered by Revenue Scotland, with its own separate rates and bands. Wales similarly uses Land Transaction Tax (LTT), administered by the Welsh Revenue Authority, rather than SDLT. A landlord or business owner incorporating a property business in Scotland or Wales needs to calculate the land transfer tax cost under the relevant devolved regime, not the SDLT figures that would apply to an equivalent transfer in England or Northern Ireland, even though the CGT and incorporation relief analysis itself remains identical across all four nations.
Practical Steps Worth Taking
- Build the incorporation relief claim into the completion process itself for any transfer from 6 April 2026 onward, rather than treating it as something to address later when the Self Assessment return is prepared.
- Where a property letting business is being incorporated, gather contemporaneous evidence of the time and range of activity genuinely involved in managing the portfolio well before the transfer, since this evidence is what determines whether a “business” exists for relief purposes at all.
- Get a proper, defensible valuation of goodwill and any property before the transfer, since this figure drives both the CGT computation and, for property, the SDLT, LBTT, or LTT charge.
- Model whether claiming the relief or deliberately not claiming it, to use BADR, capital losses, or the annual exempt amount instead, produces the better outcome, rather than assuming deferral is automatically preferable.
- If property is involved, calculate the correct land transfer tax, SDLT, LBTT, or LTT depending on where the property sits, since this is a genuine cash cost incorporation relief does nothing to reduce.
Key Takeaways
Incorporation relief remains one of the more valuable reliefs available to a growing business owner, but the shift from an automatic relief to a claim-based one from 6 April 2026 changes the practical risk profile considerably. Getting the underlying conditions right, particularly the genuinely contested “business” test for property portfolios, and treating the claim itself as an essential part of the transaction rather than an afterthought, is now the difference between a properly deferred gain and an unplanned tax bill on assets that have already left personal ownership.
Frequently Asked Questions
Do I still get incorporation relief automatically if I meet the conditions?
Not for transfers on or after 6 April 2026. You must now actively claim the relief on your Self Assessment return for the tax year of the transfer, including details of the transaction and the tax computation, a change introduced by Finance Act 2026.
What happens if I forget to claim incorporation relief after incorporating my business?
Because the relief is no longer automatic, failing to make the claim means you have, in principle, not obtained relief on the transfer, potentially leaving an unplanned CGT liability on assets that have already been transferred to the company.
Does incorporation relief apply to my goodwill?
Yes, goodwill qualifies for incorporation relief and the CGT gain can be deferred into the base cost of your shares. However, if you hold 5% or more of the company’s shares, the company cannot claim a Corporation Tax deduction for amortising that goodwill, so there is no ongoing Corporation Tax benefit to the company.
Can I incorporate my rental property portfolio and get this relief?
Only if your letting activity genuinely amounts to a business rather than passive investment. Following Elizabeth Moyne Ramsay v HMRC, this generally requires a substantial, active level of personal involvement in managing the portfolio, with around 20 hours a week cited as the benchmark in that case, rather than delegating everything to a managing agent.
Do I still pay Stamp Duty Land Tax if I incorporate a property business?
Yes. SDLT is charged separately from CGT, at the property’s market value because the transfer is between connected persons, and incorporation relief does nothing to reduce or defer this charge.
Can I choose not to claim incorporation relief if I’d rather pay CGT now?
Yes. Since the relief now requires an active claim, you can simply not make the claim if you prefer to crystallise the gain now, for example to use Business Asset Disposal Relief, unused capital losses, or your annual exempt amount.
Does receiving some cash alongside shares affect the relief?
Yes. Relief is restricted proportionally where part of the consideration for the transfer is cash or a director’s loan account credit rather than shares, with the cash portion of the gain remaining chargeable to CGT immediately.
Is Stamp Duty Land Tax the same across the whole of the UK for an incorporation?
No. SDLT applies in England and Northern Ireland, while Scotland charges Land and Buildings Transaction Tax and Wales charges Land Transaction Tax on property transferred as part of an incorporation, each with their own separate rates.
Do I need to transfer every asset of my business to get incorporation relief?
Yes, generally. You must transfer the whole of the business as a going concern, including all its assets other than cash. Deliberately retaining a valuable asset, such as a single property from a larger portfolio, will usually disqualify relief on the assets that are transferred.
About the Author:

Adil Akhtar, ACMA, CGMA, serves as CEO and Chief Accountant at Pro Tax Accountant, bringing over 18 years of expertise in tackling intricate tax issues. As a respected tax blog writer, Adil has spent more than three years delivering clear, practical advice to UK taxpayers. He also leads Advantax Accountants, combining technical expertise with a passion for simplifying complex financial concepts, establishing himself as a trusted voice in tax education.
Email: adilacma@icloud.com
Disclaimer:
The content provided in our articles is for general informational purposes only and should not be considered professional advice. Advantax Accountants strives to ensure the accuracy and timeliness of the information but makes no guarantees, express or implied, regarding its completeness, reliability, suitability, or availability. Any reliance on this information is at your own risk. Note that some data presented in charts or graphs may not be 100% accurate.
We encourage all readers to consult with a qualified professional before making any decisions based on the information provided. The tax and accounting rules in the UK are subject to change and can vary depending on individual circumstances. Therefore, PTA cannot be held liable for any errors, omissions, or inaccuracies published. The firm is not responsible for any losses, injuries, or damages arising from the display or use of this information.